Most people looking for benefits information are not browsing. They have a letter in front of them, a deadline they half understand, and a knot in their stomach.
The official guidance is all published, and it is better written than people expect. The trouble is that it is long, spread across dozens of pages, and written to be complete rather than to answer the one thing you need at 11pm. So people ask in Facebook groups instead, and that is where the bad information lives.
Here are six of the questions that come up most, with the answer from the official guidance, and a link so you can check it yourself.
Table of Contents
1. Can you work while claiming PIP?
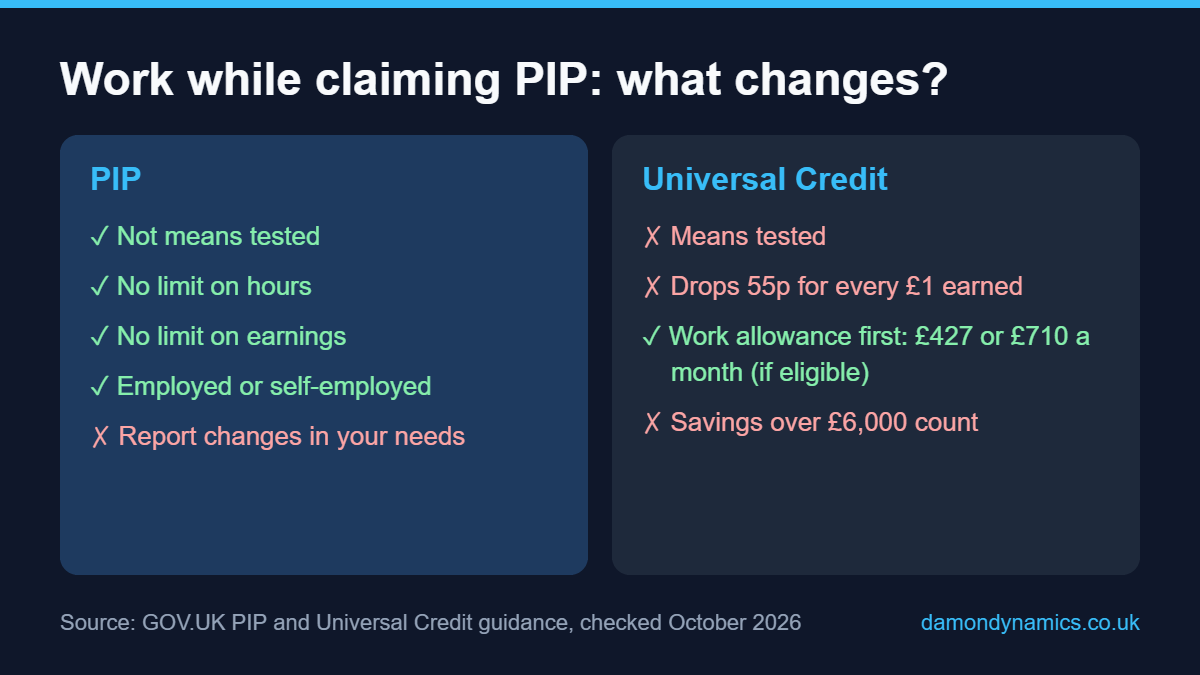
Yes, you can work while claiming PIP. Personal Independence Payment is not means tested, so it is not affected by your earnings, your hours, your savings, or most other benefits you receive.
PIP is not paid because you cannot work. It is paid because a long-term health condition or disability makes everyday tasks or getting around harder, and those things cost money. The assessment scores how your condition affects twelve activities, not what your job title is.
What does matter is honesty about how your condition affects you. If work is possible only on good days, or with adjustments, or leaves you unable to do anything else that evening, that is part of the picture, and it belongs on the form. And if your needs change, you have to tell the DWP.
So the short answer is that you can work while claiming PIP, but your form should describe your bad days as well as your good ones.
Official guidance: PIP eligibility on GOV.UK.
How many hours can you work while claiming PIP?
There is no limit. GOV.UK says you can get PIP even if you are working, and because it is not means tested there is no cap on the hours you work or what you earn. People claim PIP while working part time, full time, or running their own business.
Can you work full time while claiming PIP?
Yes. A full-time job does not stop PIP on its own. The DWP looks at how your condition affects your daily life and getting around, not at whether you have a job. If starting work or changing your hours goes with a change in your condition, for example your needs have eased, you must report the change, and your award may be looked at again.
Working while claiming PIP and Universal Credit
This is where your hours do matter, because Universal Credit is means tested. For every £1 you earn from working, your Universal Credit goes down by 55p. If you are responsible for a child, or you have a health condition or disability that affects your ability to work, you can earn a set amount first, called the work allowance: £427 a month if you get help with housing costs through Universal Credit, or £710 a month if you do not.
Official guidance: How your wages affect Universal Credit on GOV.UK.
A worked example
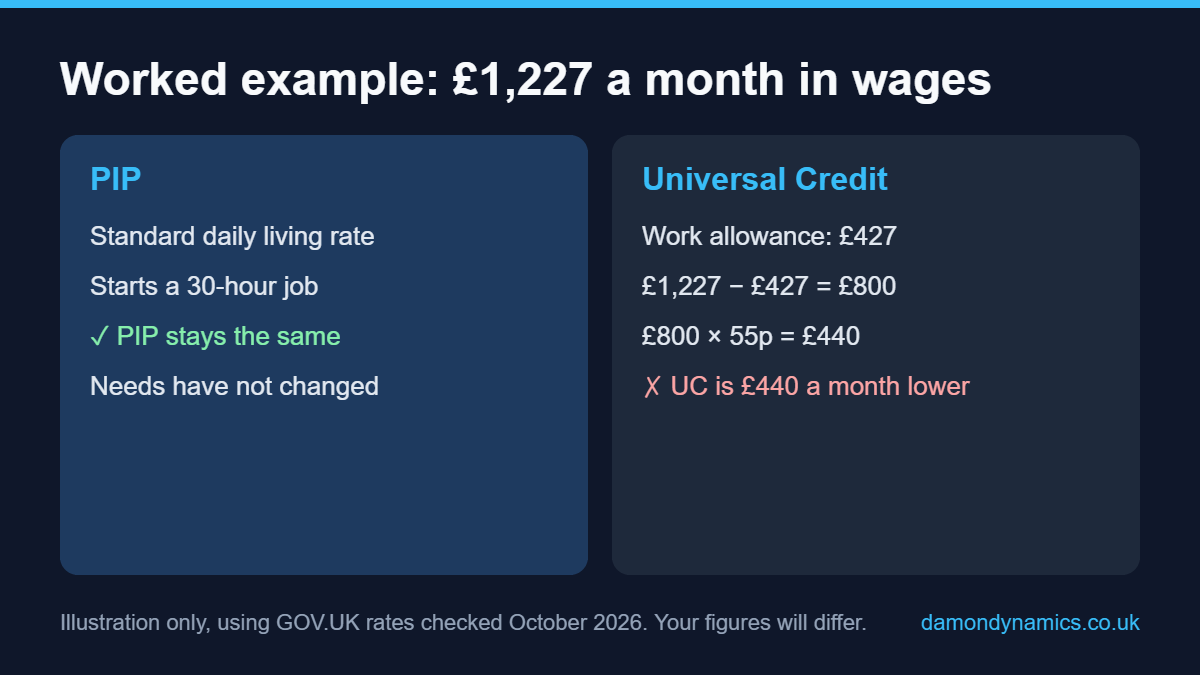
Take Sam, who has arthritis and gets the standard rate of the daily living part of PIP. Sam starts a 30-hour office job paying £1,227 a month after tax. Sam’s PIP stays the same, because the job does not change how Sam manages the twelve activities the assessment looks at.
Sam also gets Universal Credit with help towards rent, and has been assessed as having limited capability for work, so the £427 work allowance applies. The first £427 of wages makes no difference. The other £800 reduces Universal Credit by 55p in every pound, which is £440 a month. Sam is still better off working, by £787 a month, before any travel or other costs.
Do you have to tell the DWP you have started work?
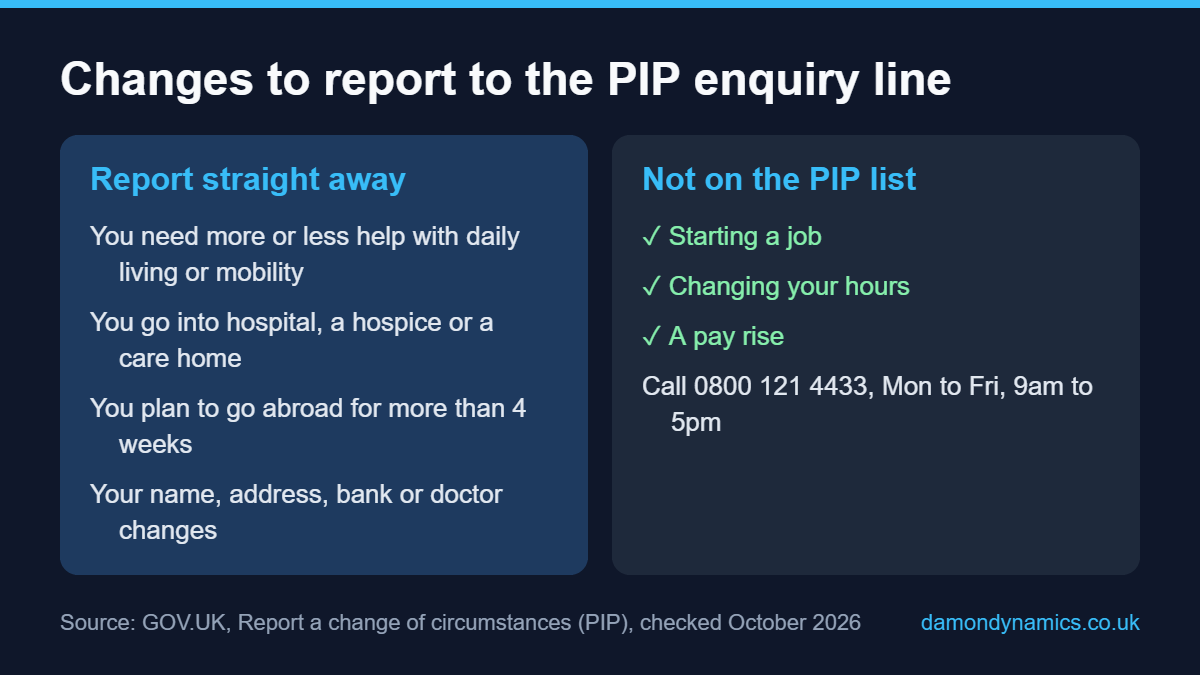
Not for PIP on its own. Starting a job is not on the GOV.UK list of changes you must report for PIP. What is on the list is a change in how much help you need with daily living or getting around. So if you work while claiming PIP and your condition has not changed, the job itself is not something you have to ring about.
If the job does come with a change, for example new equipment means you need less help, or the commute is making your mobility worse, that change in your needs is what you report. Call the PIP enquiry line on 0800 121 4433, Monday to Friday, 9am to 5pm. Relay UK users can dial 18001 first.
Universal Credit works differently. If your employer pays you through PAYE, your earnings reach the DWP automatically, and if you are self-employed you report your earnings each month in your online account. Either way, your Universal Credit payment can change even when your PIP stays exactly the same.
Not reporting a change you should have reported can mean paying money back. GOV.UK warns that giving wrong information, or not reporting a change straight away, can lead to a penalty or even court. If you are unsure whether something counts, ring and ask. It is a normal question and nobody will think less of you for it.
Working while claiming PIP if you are self-employed
The PIP rule is the same. PIP does not look at whether you are employed or self-employed, how many hours you put in, or how much profit you make. If you also claim Universal Credit, self-employment brings its own rules, including the minimum income floor, which can assume you earn a set amount once you have been trading for a while. Check the GOV.UK self-employment guidance for Universal Credit before you rely on any figure.
Volunteering, and what changes if you also get ESA
Volunteering does not affect PIP either. As with paid work, what matters is how your condition affects you. If you also get Universal Credit, tell your work coach about any volunteering, because it can shape what you are asked to do as part of your claimant commitment.
If you get Employment and Support Allowance as well as PIP, be more careful. ESA has its own permitted work rules, with limits on hours and earnings, so check those before you start a job. Those limits belong to ESA, not PIP.
Access to Work: help at work that sits alongside PIP
If your condition makes work harder, Access to Work is worth knowing about, and far fewer people use it than could. It is a grant, not a loan, so you do not pay it back, and GOV.UK says getting it will not affect any other benefits you receive.
It can pay for practical support: specialist equipment and software, a support worker such as a BSL interpreter or job coach, extra travel costs if you cannot use public transport, and changes to your workplace. Your home counts as a workplace if you work from there. There is also mental health support, with a tailored plan and one-to-one sessions with a mental health professional.
It does not cover the reasonable adjustments your employer already has to make by law, but Access to Work can advise your employer on those. Official guidance: Access to Work on GOV.UK.
Common mistakes when you work while claiming PIP
- Describing only your good days. If you can work three days a week but spend the other four recovering, that belongs on the form.
- Assuming a job means PIP will stop. It will not, unless your needs change.
- Forgetting Universal Credit is means tested. Plan for your Universal Credit to fall when your pay goes up, even though your PIP does not.
- Saving changes for your next review. Report a change in your needs when it happens, not when the review letter arrives.
- Trusting a Facebook group over GOV.UK. Rules about work and benefits get garbled fast. Check the official page before you act on anything.
2. How much is PIP in 2026?
PIP has two parts, daily living and mobility, and each is paid at either a standard or an enhanced rate depending on your points. You need 8 points for the standard rate of a component, and 12 for the enhanced rate.
For 2026/27 the weekly rates are £76.70 or £114.60 for daily living, and £30.30 or £80.00 for mobility. Someone awarded the enhanced rate of both gets £194.60 a week. The rates rose by 3.8% in April 2026, in line with the annual uprating. PIP is tax free and normally paid every four weeks.
Official guidance: PIP payment rates on GOV.UK.
3. Will savings stop your Universal Credit?
Unlike PIP, Universal Credit is means tested, so savings do count. The rules are less brutal than the rumours, though.
Up to £6,000 is ignored completely. Between £6,000 and £16,000, the DWP treats your savings as if they produce a small income: £4.35 a month for every £250, or part of £250, above £6,000. So £8,000 in savings means about £34.80 a month less, whatever your account actually pays in interest. At £16,000 the entitlement stops.
For a couple, savings are added together, whether you claim jointly or not.
Official guidance: Universal Credit eligibility on GOV.UK.
4. Why does the first Universal Credit payment take five weeks?
Because Universal Credit is worked out over a monthly assessment period and then paid a week later. The wait is built into the design, not a delay in your case.
If that gap is going to leave you short, you can ask for an advance. It is a loan, with no interest, repaid out of your later payments, and you can ask for it through your online account or your work coach. Ask early rather than at the end of the wait.
After the first payment, you are paid on the same date each month. If the date falls on a weekend or a bank holiday, you are paid on the working day before. In Scotland you can choose to be paid twice a month.
Official guidance: How you’re paid on GOV.UK.
5. Is PIP being cut in 2026?
This is the question causing the most fear, and the answer is calmer than the rumours.
A proposed rule that would have required 4 points in a single daily living activity was removed from the Universal Credit and Personal Independence Payment Bill in July 2025 and did not become law. The November 2026 start date people still quote belonged to that scrapped proposal.
Separately, the Timms Review is looking at how PIP is assessed. Its interim report came out in July 2026 and it is due to report fully in autumn 2026. A review is not a rule change: any change to eligibility would need new legislation through Parliament first. The activities, descriptors and points used today are the same ones used before.
One real change did happen in June 2026: the DWP can now set longer gaps between award reviews. If you got a letter saying your award has been extended, it means you are not being called back for reassessment yet.
If you see a post claiming your PIP is about to stop, check it against GOV.UK before you lose a night’s sleep over it. And never pay anyone who offers to protect your award. That is a scam.
6. What can you do if the decision seems wrong?
You ask for a mandatory reconsideration, which is the DWP looking at the decision again. You normally have one month from the date on the decision letter, so this is the deadline to diary the day the letter arrives. If the answer still seems wrong, you can appeal to an independent tribunal, again normally within one month.
Do not let the deadline pass while you work out what to say. Citizens Advice can help you with both stages, free.
Official guidance: Appeal a benefit decision on GOV.UK.
If you live in Scotland
New disability claims in Scotland go through Adult Disability Payment, run by Social Security Scotland, rather than PIP. Universal Credit still comes from the DWP. If you are reading PIP guidance for a new Scottish claim, you are reading the wrong page.
Where these answers came from
Whether you can work while claiming PIP, what savings do to Universal Credit, how the five-week wait actually works: it is all in the official guidance. Finding it is the hard part.
That is why we built Plainly Benefits, a free tool that does this work for you. You ask a question in your own words, and it answers in plain English using only official GOV.UK guidance on PIP, Universal Credit and appeals. Underneath each answer are numbered links to the exact pages it used, so you can check it in one click.
It works differently from a general chatbot. It has no general knowledge to fall back on: it searches the guidance first and answers only from what it finds. If your question is not covered, it says so and points you to Citizens Advice instead of guessing. That refusal is the most important feature in the whole thing. Wrong benefits information can cost someone money they cannot spare.
It runs in a browser on any phone, installs to your home screen if you want it there, and costs nothing. There is no account and no sign-up, and your questions are not stored. It is not affiliated with the DWP or GOV.UK, and it is not a replacement for advice about your own claim.
If you are also waiting on NHS treatment, we wrote about what you can do while you wait.
Where to get help from a person
An app can find the guidance. It cannot sit with you while you fill in a form, and it cannot argue your case.
- Citizens Advice can help you check what you can claim, fill in forms and challenge decisions, for free.
- Turn2us has a benefits calculator and a grants search.
- Your local council may fund a welfare rights service, and many disability charities have advisers who know one condition very well.
If you are struggling with the form, get help before the deadline rather than after it.
Information in this article was checked against GOV.UK guidance in October 2026. Benefits rules change, so check the linked pages for the current position. This is information, not advice about your own claim.